Fully Diluted Shares: How to Calculate Ownership Correctly
Fully diluted shares are the total number of shares a company would have if every share it has promised were actually issued: all common stock, preferred stock counted as if converted to common, every granted option and warrant, the unallocated option pool and, when a round is priced, SAFEs and convertible notes as if converted. Ownership on a fully diluted basis is your shares divided by that total. It sets the price per share in a priced round, and it is usually much lower than the percentage you get by dividing by issued shares alone. But there is no single definition: the term sheet, a SAFE, the investor rights agreement and a merger agreement each count slightly different things.
Most ownership mistakes in startups come from using the wrong denominator. This guide explains what goes into a fully diluted share count, which version each document uses, a full worked example from SAFE to Series A, real disputes over the term, and what employees should ask before accepting an equity offer.
1. Authorised, Issued, Outstanding and Fully Diluted
- Authorised shares: the maximum number of shares the charter allows the company to issue. It is a legal ceiling and says nothing about ownership.
- Issued and outstanding shares: shares actually issued to holders, such as founder common stock and investors' preferred stock. This is the base for voting, because options and the unallocated pool carry no votes.
- Fully diluted shares: outstanding shares plus every share the company is committed or has reserved to issue. This is the base for pricing a round and for most ownership percentages.
What a fully diluted count includes
- All common stock, including founder shares that are still vesting
- All preferred stock, counted on an as-converted basis
- All granted options and restricted stock units, vested and unvested
- Warrants, for example those issued to venture lenders
- Promised options: grants in signed offer letters that the board has not yet approved
- The unallocated option pool, meaning shares reserved for future grants
- SAFEs and convertible notes, as if converted, when a round is being priced
As our guide to the option pool shuffle explains, the unallocated pool counts against everyone from the day it is created, even if no options are ever granted from it.
2. Which Denominator Each Document Uses
The phrase "fully diluted" changes meaning from one document to the next. The biggest difference is whether the unallocated pool is counted.
- Term sheet pricing (counts the pool): the National Venture Capital Association (NVCA) model term sheet sets the Series A price from a fully diluted pre-money valuation that includes an unallocated option pool, sized as a percentage of the fully diluted post-money capitalisation (NVCA model documents). The NVCA updated its definitive documents in 2025 and 2026, but the model term sheet it posts is still the 2020 version.
- Post-money SAFE conversion (counts the existing pool): the YC SAFE's "Company Capitalization" counts issued shares, every SAFE and convertible note, granted and promised options and the existing unallocated pool, but not a pool increase made for the priced round (section 4).
- SAFE payout on an early sale (excludes the pool): if the company is sold before a priced round, the SAFE uses "Liquidity Capitalization", which excludes the unallocated pool.
- Anti-dilution (excludes the pool): in the NVCA broad-based weighted average formula, the share base counts outstanding common, preferred as converted and outstanding options, but not the unissued pool. See anti-dilution protection.
- Pro rata rights (excludes the pool): the NVCA Investors' Rights Agreement measures a major investor's share against all outstanding stock, assuming conversion and exercise of outstanding preferred, options and other derivative securities. The unissued pool is not counted. See pro rata rights.
- Voting (issued shares only): preferred usually votes with common on an as-converted basis. Options and the pool do not vote.
- M&A (usually excludes the pool): merger agreements typically divide the price by a fully diluted count that leaves out the unissued pool, because nobody holds those shares. This is negotiable: a buyer planning to keep the pool may want it counted.
- Public company accounting (treasury stock method): diluted earnings per share under US GAAP (ASC 260) or IFRS (IAS 33) counts only the net new shares from in-the-money options and never an unissued plan reserve. If a company has 1,000,000 options with a $1 strike and a $4 share price, the method adds 750,000 shares, because the exercise money is assumed to buy back 250,000 shares.
3. The Formulas
Fully diluted ownership = your shares (as converted) ÷ total fully diluted shares
Price per share in a priced round = pre-money valuation ÷ pre-money fully diluted shares
The second formula is where the definition matters most. Every share counted in the pre-money total, including the option pool, its increase for the round and converting SAFEs, lowers the price per share. A lower price gives the new investor more shares for the same money, and the extra dilution falls on existing holders. That is why two term sheets with the same headline valuation can leave founders with very different stakes.
4. How SAFEs Fit In
- Post-money SAFE: the conversion price is the post-money valuation cap divided by the Company Capitalization. Because every SAFE is counted, each holder's stake is fixed in advance at roughly the investment divided by the cap. A $1 million SAFE at a $10 million cap buys 10% of the capitalisation before the priced round, and every later SAFE dilutes the founders rather than earlier SAFE holders (YC SAFE documents).
- The pool increase: a pool increase made for the priced round is left out of the Company Capitalization, so it dilutes founders and SAFE holders, not the new investor. The one exception is where promised options already exceed the existing pool.
- Pre-money SAFE: the older form left other SAFEs out of the count but included the new-round pool increase, so SAFE holders diluted one another and nobody knew their stake until the round priced.
- Before conversion: a SAFE is not a share and does not appear in the issued count. Cap table models usually show it as converted at the cap, which is an estimate until the round sets the price. In Carta's data, only 29% of seed rounds raised in the first three quarters of 2026 by companies with earlier SAFEs converted them below the cap (Carta, State of Pre-Seed Q3 2026), so modelling at the cap is usually right.
- Stacking: post-money SAFEs add up for founders. For example, $500,000 at a $6 million cap (8.3%) plus $2 million at a $12 million cap (16.7%) costs about 25% before the seed investor takes its share.
For more on conversion, see how SAFE notes work and MFN clauses in SAFEs.
5. Worked Example: From SAFE to Series A
Starting point:
- Founders: 8,000,000 common shares
- Options granted to employees: 1,000,000
- Unallocated option pool: 1,000,000
- Fully diluted total: 10,000,000 shares
- Outstanding: a $1 million post-money SAFE at a $10 million valuation cap
What the founders think they own: 8,000,000 of the 8,000,000 issued shares, or 100%. On a fully diluted basis it is 80% (8,000,000 ÷ 10,000,000). Counting the SAFE, which will take 10% of the company capitalisation, it is 72%.
Step 1: the SAFE converts
- Company capitalisation: 10,000,000 ÷ (1 − 10%) = 11,111,111 shares
- SAFE shares: 11,111,111 − 10,000,000 = 1,111,111
- SAFE price: $10,000,000 ÷ 11,111,111 = $0.90 a share
Step 2: the Series A is priced
The lead invests $5 million at a $20 million pre-money valuation, so the post-money is $25 million and the investor owns 20%. The term sheet requires an unallocated pool of 10% of the post-money fully diluted shares, created in the pre-money. As is most common in the US, the converted SAFE shares also sit in the pre-money; the term sheet should say so explicitly.
- Founders, granted options and SAFE shares (10,111,111) must equal 70% of the post-money total, because the Series A takes 20% and the pool 10%.
- Post-money fully diluted shares: 10,111,111 ÷ 0.70 = 14,444,444
- Price per share: $25,000,000 ÷ 14,444,444 = $1.7308
- Series A shares: 2,888,889. (Share counts are worked out from the unrounded price; dividing $5 million by the rounded $1.7308 would give about 52 fewer shares.)
- Unallocated pool: 10% × 14,444,444 = 1,444,444, an increase of 444,444
- Check: pre-money fully diluted shares are 11,555,556, and $20,000,000 ÷ 11,555,556 = $1.7308.
Step 3: the post-money cap table
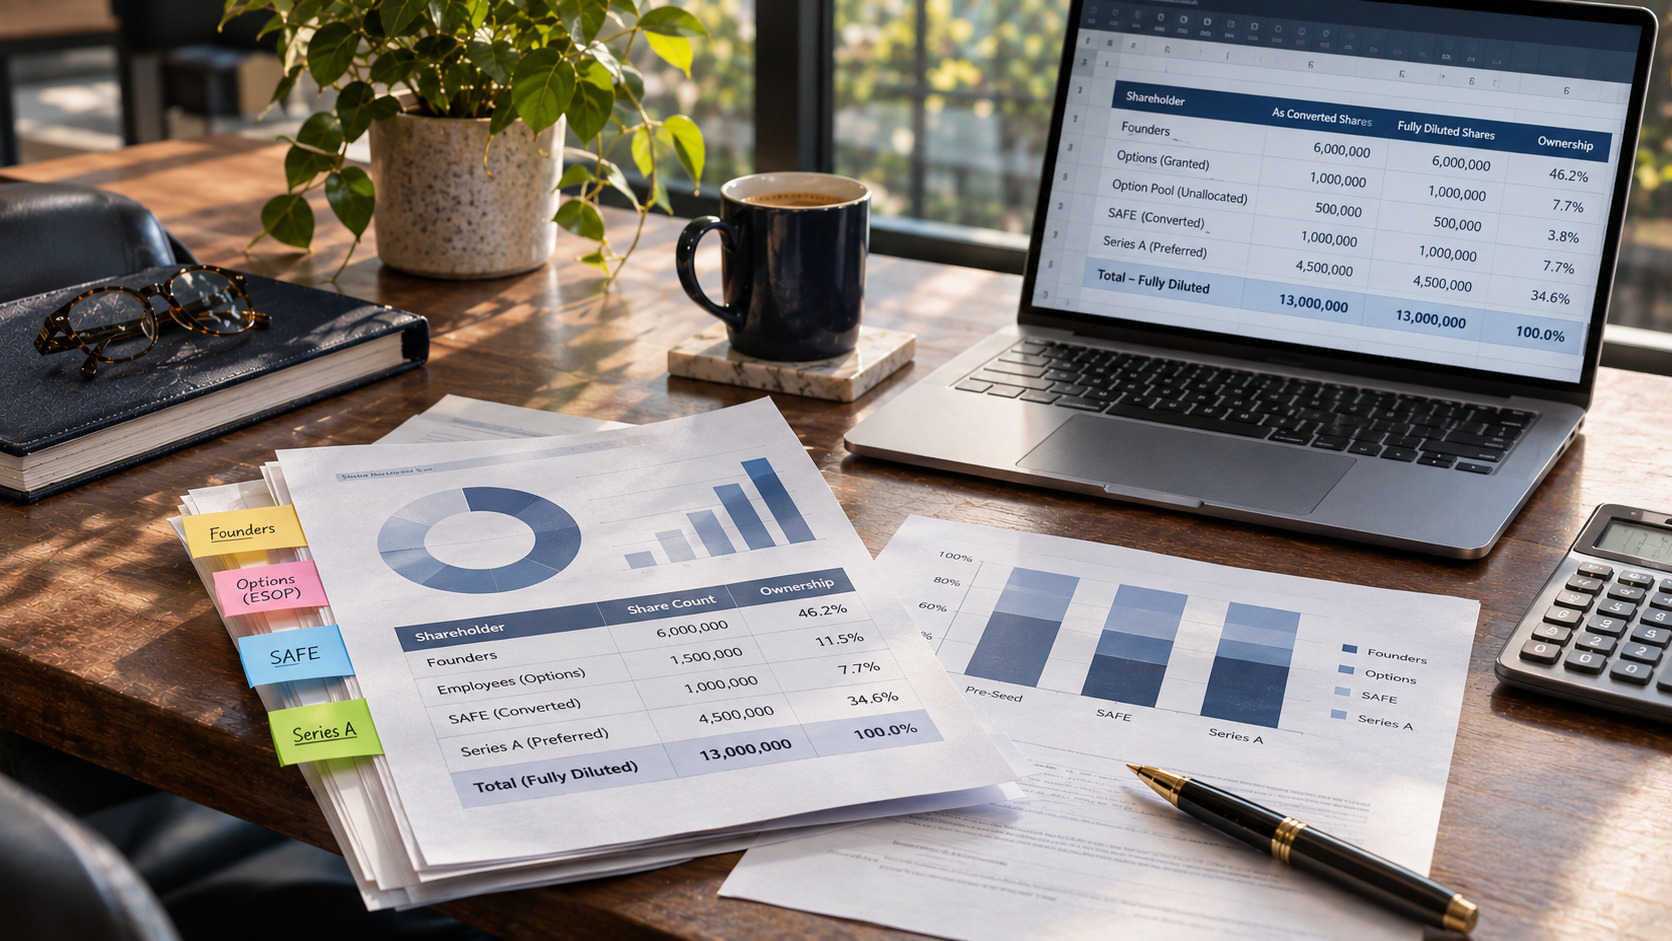
- Founders: 8,000,000 shares, 55.4%
- Granted options: 1,000,000, 6.9%
- Unallocated pool: 1,444,444, 10.0%
- SAFE investor: 1,111,111, 7.7%
- Series A investor: 2,888,889, 20.0%
- Total: 14,444,444, 100%
The same cap table, four different percentages
- Fully diluted (pricing basis): founders own 55.4%.
- Issued shares (voting basis): 12,000,000 shares are issued (founders, SAFE preferred and Series A preferred), so founders hold 66.7% of the votes.
- Rights basis (anti-dilution and pro rata): excluding the unissued pool, the base is 13,000,000 shares. The Series A's pro rata share for the next round is 22.2%, not 20%.
- Large sale: if the company sells for a high price and the pool is excluded, founders receive 61.5% of the proceeds (8,000,000 ÷ 13,000,000), before option exercise prices.
What the pool increase cost
Without the pool increase, the price would have been $20,000,000 ÷ 11,111,111 = $1.80 a share, the Series A would have received 2,777,778 shares, and the founders would own 57.6% fully diluted. Putting the pool increase in the pre-money cost the founders 2.2 percentage points and the incoming investor nothing. Measured at the round price, the existing holders' 10,000,000 shares are worth $17.3 million, not $20 million, because the SAFE conversion and the pool increase both sit inside the pre-money.
What a percentage is worth in a small exit
Fully diluted percentages ignore liquidation preferences. If this company sold for $10 million with 1x non-participating preferred, the Series A would take its $5 million preference, the SAFE preferred its $1 million, and the remaining $4 million would be shared by common and option holders. Founders would receive about $3.56 million, or 35.6% of the proceeds, against their 55.4% fully diluted stake.
6. When the Definition Ends Up in Court
- Cannon v. Romeo Systems (Delaware Court of Chancery, October 2025): a consultant was offered a warrant for 1% "on a fully diluted basis". His lawyer changed the measurement date from the time of issuance to the time of exercise, and the CEO signed without reading the change. The court found the consultant entitled to damages based on 965,246 warrant shares, against the 121,730 shares the company had in mind. When fully diluted is measured matters as much as what it counts.
- The Kensho dispute (Crawford-Brunt v. Kruskall, D. Mass.): an investor agreed to buy 2% of Kensho's "fully diluted" shares for $2 million, and the parties filed competing expert reports on what the phrase meant. The case went to a jury, which found for the defendant after evidence that the investor had been told he was buying 2% of issued and outstanding shares.
The lesson: whenever a percentage appears in a contract, define the denominator, list what it includes and state the date it is measured.
7. Common Mistakes
- Using authorised shares as the denominator.
- Leaving out the unallocated pool when pricing a round or sizing a grant.
- Ignoring SAFEs and convertible notes before the first priced round.
- Forgetting warrants and promised grants, such as venture lender warrants or options in signed offer letters.
- Double counting, for example counting exercised options both as options and as common stock.
- Mixing pre-money and post-money SAFE maths.
- Applying one definition everywhere. A 20% stake for pricing can be 22.2% for pro rata and a different figure again in a sale.
- Quoting a percentage with no share count or date.
8. What Employees Should Ask About an Equity Offer
Best practice is for an offer to state a number of shares, with the percentage shown as an illustration on a stated date, for example "50,000 options, about 0.35% of fully diluted capitalisation as of 1 November 2026". Before accepting, ask for:
- The total fully diluted share count, and whether it includes the unallocated pool and outstanding SAFEs and notes.
- The strike price (set by the 409A valuation of common stock) and the latest preferred price paid by investors.
- The total liquidation preferences ahead of common stock.
- Vesting, cliff and any acceleration.
- The exercise window after leaving, often 90 days, and whether the options are ISOs or NSOs.
- Confirmation that the board grant matches the offer letter.
In the worked example, a 50,000-option grant is 0.35% fully diluted after the Series A but 0.42% if someone divides by issued shares only. For context, Carta's H1 2026 compensation data put the median grant for a startup's first hire at 1.75% (Carta, State of Startup Compensation H1 2026). Expect any percentage to shrink with each future round, even as the value of the shares rises.
9. What the Data Shows
- Founder ownership: Carta's Founder Ownership Report 2026 (March 2026, rounds raised 2021 to 2025) found the median founding team holds about 56% after seed, 36% after Series A, 23% after Series B and 16.1% after Series C. By Series C the median employee pool (16.8%) is larger than the founders' stake (Carta, 2026).
- Option pools: the median seed-stage pool is about 12% after the round: 12.1% in the 2026 report, and 11.8% in an earlier Carta cut of more than 15,000 startups, which also found most companies use only 60% to 70% of the pool before the next raise (Carta, 2025).
- Dilution per round: Carta's Q2 2026 medians were 19.4% at seed, 18.7% at Series A and 13.4% at Series B (Carta Series A guide).
- Pool top-ups: HSBC Innovation Banking's 2026 US financings guide, covering more than 500 signed deals, found two-thirds of rounds create or expand the option pool (HSBC Innovation Banking).
These are medians and the spread is wide, but the pattern is clear: a SAFE round, a seed and a Series A, each with a pool top-up, usually leave the founding team with well under half of the fully diluted company.
10. UK and Europe
- Same concept, open denominator: UK term sheets refer to the "fully diluted share capital". The BVCA model term sheet offers bracketed choices for whether the option pool is measured against shares in issue before completion, after completion or on a fully diluted basis, so the denominator is openly negotiated.
- Pre-money or post-money pools: US pools are usually created in the pre-money. HSBC's 2024 UK guide found a new pool or top-up in 72% of UK term sheets, and half of those were calculated in the post-money.
- EMI options count in fully diluted share capital like any other option; EMI status affects tax, not the cap table maths. For grants from 6 April 2026, the EMI limits rose to 500 employees, £120 million of gross assets and £6 million of shares under option.
- Advance subscription agreements (ASAs) play a role similar to SAFEs; see ASA vs SAFE.
Frequently Asked Questions
What are fully diluted shares?
All outstanding shares plus every share that could be issued under existing rights: preferred as converted, granted options and RSUs, warrants, promised options, the unallocated pool and, when pricing a round, SAFEs and notes as converted.
What is the difference between fully diluted and outstanding (basic) shares?
Outstanding shares are actually issued and decide voting. Fully diluted shares add everything the company has promised or reserved, and decide pricing and grant percentages.
Does fully diluted include the unissued option pool?
For term sheet pricing and post-money SAFE conversion, yes. For SAFE payouts on an early sale, NVCA anti-dilution and pro rata rights, most merger payouts and public company diluted EPS, no.
Are SAFEs included in fully diluted shares?
The post-money SAFE counts every SAFE and convertible note when it converts, and cap tables usually show SAFEs as converted at the cap. They are not issued shares until the priced round.
What is the fully diluted shares formula?
Common + preferred (as converted) + granted options, RSUs and warrants + promised options + unallocated pool + SAFEs and notes (as converted) = fully diluted shares.
How do you calculate fully diluted ownership after a round?
Convert the SAFEs, size the pool as a percentage of the post-money, then divide the pre-money valuation by pre-money fully diluted shares to get the price, as in the worked example above. Your ownership is your shares divided by the post-money total.
Why does my percentage keep falling if the company is doing well?
Each round, pool top-up and SAFE conversion adds shares. Your share count stays the same while the total grows, so your percentage falls even as the value per share rises.
The Bottom Line
Fully diluted ownership is the honest measure of who owns a startup, but it is not one number. Count every share the company has issued, promised or reserved when you price a round or size a grant, then check which definition each document uses for anti-dilution, pro rata, voting and a sale. In any contract that quotes a percentage, define the denominator and the date. Model the cap table before you sign. Look up related terms in the GCN glossary.
Global Capital Network connects founders with angels, venture funds and family offices through our investor conferences and private investor dinners. Explore our glossary or get in touch to learn more.
This article is general information, not legal, tax or investment advice. Share counts and definitions vary by company and document, so check your own term sheet, SAFEs and cap table with qualified counsel.