





Investor Relations & Capital Introduction Services in Indonesia
Indonesian startups raised approximately US$355.7 million in equity across 91 deals during 2025. In the same year, they raised roughly US$264 million in debt financing across just eight transactions.
Eight debt deals delivered nearly as much capital as ninety-one equity rounds. That comparison is the most important thing on this page, because it describes a market where companies with revenue have started borrowing rather than diluting, and where the financing conversation has fundamentally changed.
Global Capital Network provides investor relations and capital introduction services for companies raising in Indonesia, and for allocators seeking structured access to Indonesian dealflow. Where debt has become a genuine alternative to equity, the question of which instrument a company should pursue comes before the question of which investor.
Capital Raising & Investor Introductions in Indonesia
The equity picture requires honest framing. Indonesia's 2025 total of US$355.7 million sits against a 2021 peak of approximately US$6.9 billion, meaning current equity funding is roughly five per cent of what it was four years ago. That is one of the sharpest corrections in any market covered by this network.
Deal count held up considerably better than value, at 91 against 139 at the peak. Companies are still being funded; they are being funded far less. For a founder, that means the round available is likely to be a fraction of what a comparable company raised in 2021, and plans built on those benchmarks will not survive contact with the market.
Within equity, the distribution favours later stages sharply. Pre-seed and seed rounds accounted for 62 deals, roughly 67% of all transactions, yet Series A through C captured about 80% of the capital, some US$290 million. Two thirds of the deals took one fifth of the money.
Sector concentration is clear. New retail led at approximately US$130.9 million across 15 deals, followed by financial technology at US$77.2 million across 16 deals, and e-commerce at US$35.8 million. These are categories with visible revenue and established consumer behaviour, which is consistent with investors underwriting demonstrable business models.
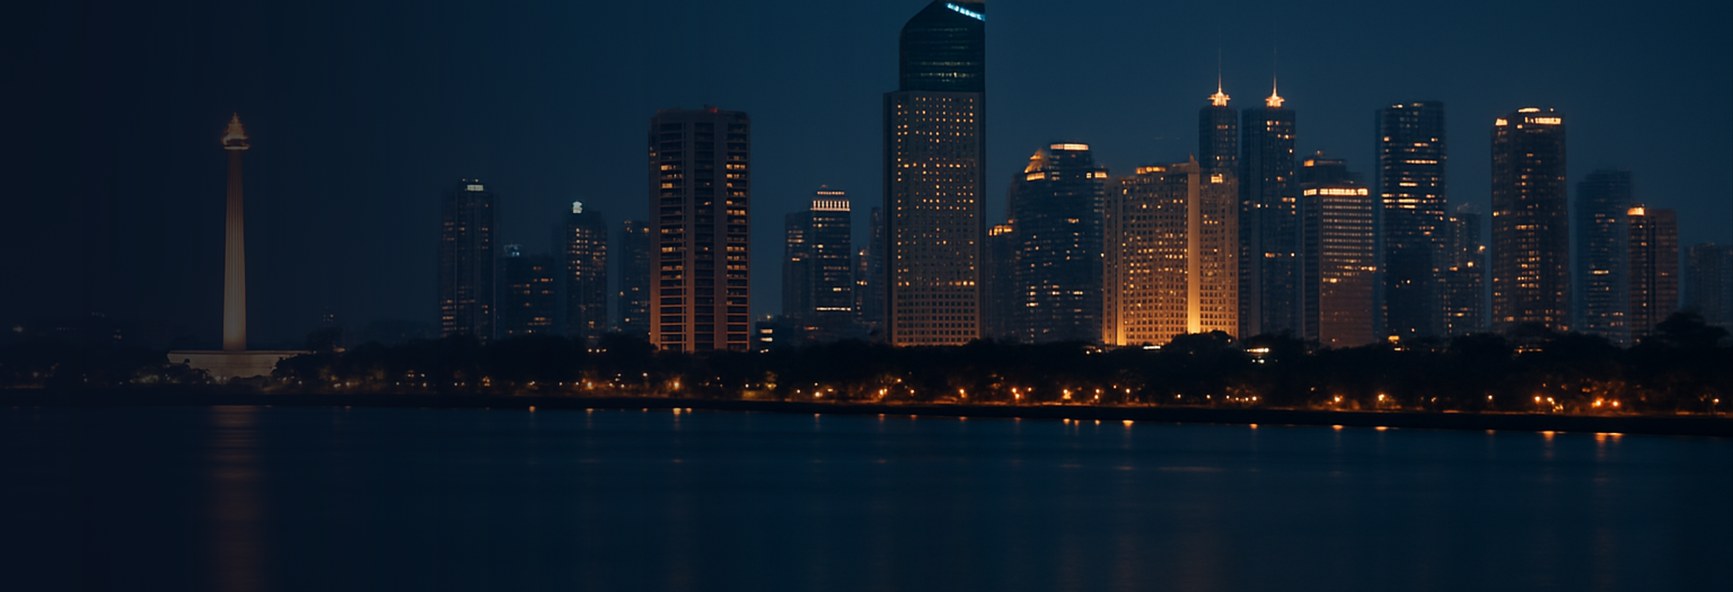
Jakarta anchors the overwhelming majority of Indonesian startup activity, with smaller activity in Surabaya, Bandung and Bali.
GCN supports Indonesian companies across seed, growth and later stages, and works with founders on whether equity or debt is the appropriate instrument for their situation.
Pitch Deck Design & Fundraising Preparation
The rise of debt financing changes the preparation question fundamentally. A company with predictable revenue may be better served borrowing against it than selling equity at valuations reset 95% from peak. That decision should be made deliberately rather than by default.
GCN works with founders on both paths. For equity, whether unit economics hold at the scale being projected, whether the path to profitability is credible on the capital being raised, and whether the commercial evidence would survive reference checks. For debt, whether cash flows are predictable enough to service an obligation and what covenants would mean operationally.
The valuation environment also demands realism. A founder benchmarking against 2021 comparables will find the market unrecognisable. Preparing against current conditions, with a round sized to what is genuinely available and milestones set accordingly, produces materially better outcomes than preparing against the market that existed four years ago.
For companies in retail, commerce and financial technology, where 2025 capital concentrated, preparation should emphasise the characteristics that attracted it: demonstrated demand, working unit economics, and operational discipline across a geographically complex market.
Investor Events, Dinners & Networking in Indonesia
Indonesia's investor community concentrates heavily in Jakarta, with a substantial proportion of the capital reaching Indonesian companies originating in Singapore. Practically, this makes the Jakarta-Singapore corridor the most important relationship axis for most Indonesian founders.
GCN convenes private investor dinners and closed sessions matched by sector and stage, with mandates verified in advance. Given the role of debt in the current market, we also compose sessions that include private credit and venture debt providers rather than equity investors alone.
Our programming addresses where Indonesian capital is actually moving: retail and commerce technology, financial technology and payments, logistics and supply chain, health technology, and energy and resources. Sessions are scheduled around the established Indonesian and Southeast Asian calendar so that visiting allocators can participate without arranging separate travel.
Investor Webinars & Digital Capital Access
With a significant share of capital originating outside Indonesia, particularly from Singapore, reaching regional and international allocators is structural rather than supplementary.
GCN runs online investor sessions connecting Indonesian founders with allocators across Southeast Asia, East Asia and beyond. These are structured for assessment rather than exposure, with short presentations, protected question time, and follow-up routed only to investors who signal genuine interest.
Hybrid formats pair a Jakarta gathering with remote attendance, extending reach to Singapore, Hong Kong, Tokyo, Sydney and San Francisco. For companies whose thesis rests on Indonesian consumer scale, this also lets investors assess that argument against comparable positions elsewhere.
Services for Investors in Indonesia
For allocators, Indonesia offers the largest consumer market in Southeast Asia attached to the region's most severely repriced equity market. Those two facts together define the opportunity and the risk.
Entry pricing has reset comprehensively. With equity funding at roughly five per cent of the 2021 peak, valuations bear no relationship to the levels that prevailed during the abundant period, and competition for individual rounds is limited.
The debt market is the more interesting development for many allocators. US$264 million across eight transactions indicates a cohort of Indonesian companies with cash flows predictable enough to support debt, which is a meaningfully different risk profile from pre-revenue venture positions and one that some mandates suit better.
The constraints are real. The scale of the equity correction reflects genuine problems in the preceding cycle, including governance gaps and companies built on unsustainable economics. An investor entering now benefits from that reset and should also understand what caused it.
GCN provides curated dealflow filtered against stated criteria rather than general distribution, and remains involved through diligence rather than stepping back at introduction.
GCN Deal Flow Platform & Investor Matching
Our platform organises Indonesian opportunities by sector, stage, geography and thesis, and distinguishes between companies seeking equity and those suited to debt or structured financing.
Matching operates on cheque size, stage preference, sector mandate and geographic scope, with attention to whether an allocator's mandate fits the equity or the credit side of the current Indonesian market.
Why Indonesia Is Attractive for Investors
Entry pricing has fully reset. Equity funding of approximately US$355.7 million in 2025 sits at roughly five per cent of the 2021 peak, meaning valuations reflect current fundamentals rather than prior enthusiasm.
Companies are creditworthy. Around US$264 million was raised through debt across just eight transactions, indicating a cohort with cash flows predictable enough to service borrowing.
Deal activity has held better than value. 91 deals closed in 2025 against 139 at the peak, meaning companies are still being funded even as cheque sizes have contracted sharply.
Capital concentrates in proven categories. Retail led at approximately US$130.9 million and fintech at US$77.2 million, showing where domestic conviction currently sits.
Partner with Global Capital Network in Indonesia
For founders raising in Indonesia, GCN provides investor relations infrastructure connecting Indonesian companies with regional and international capital, across both equity and credit. Our approach is relationship-led, and we judge our work by whether an introduction still matters two funding rounds later.
For investors seeking Indonesian exposure, we deliver curated dealflow, diligence support and relationship facilitation across the sectors where Indonesian companies are strongest. Whether you allocate as a fund, a family office, a credit provider, or a strategic acquirer, our role is to shorten the distance between your mandate and the companies that match it.
To discuss your objectives in Indonesia, whether you are based in Jakarta, Surabaya, Bandung, or engaging from international markets, our team is available to talk through how we can help.


